Profit & loss (accrual vs cash)
Who it’s for: Everyone — every role can read reports Where: Reports → Profit & loss (or click Profit this month on Books) Before you start: Nothing.
The profit & loss (P&L) shows your income, the direct costs of your jobs, your overheads, and what’s left — net income — for a period.
Accrual or cash, in plain words
Section titled “Accrual or cash, in plain words”- Accrual counts income when you invoice and costs when you’re billed or spend. It shows what you earned in the period, paid or not. It’s the default.
- Cash counts an invoice’s income only as the customer pays it — on the date each payment is applied to it — and a bill’s costs only as you pay the bill. It shows what came in and went out.
A few things work the same way on both: expenses you paid on the spot, and journal entries. The difference is only when invoices and bills count. So if a customer holds back retainage until the job is signed off, that share of the invoice counts on the cash basis when you actually collect it — not when you invoiced.
-
Open Reports → Profit & loss. It opens on Year to date, on the Accrual basis.
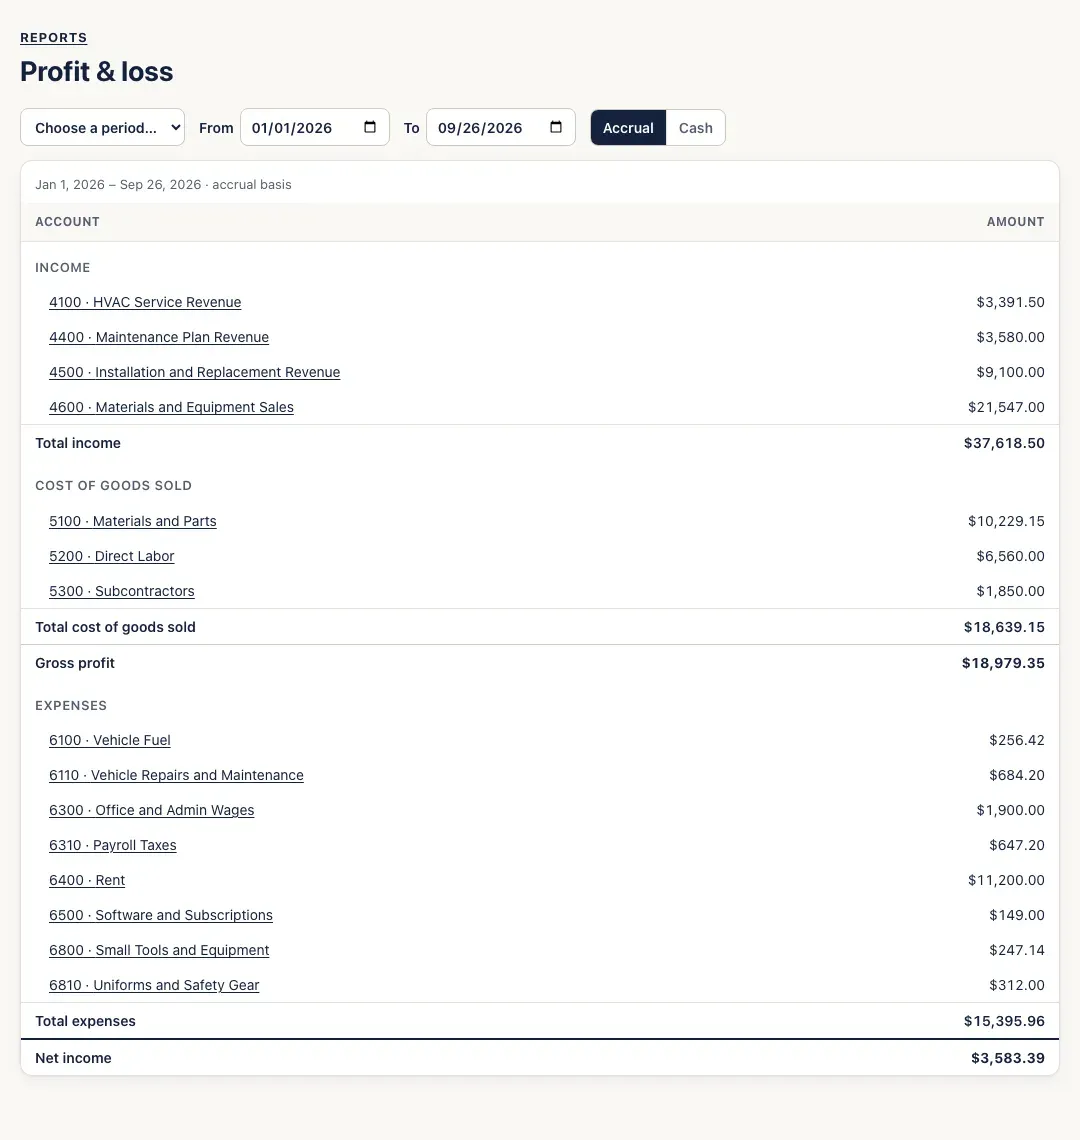
-
To change the period, choose from Choose a period… (This month, Last month, This quarter, Last quarter, Year to date, Last year), or set From and To.
-
Click Cash to see the same period on the cash basis; Accrual switches back. The line above the table says which basis you’re looking at.
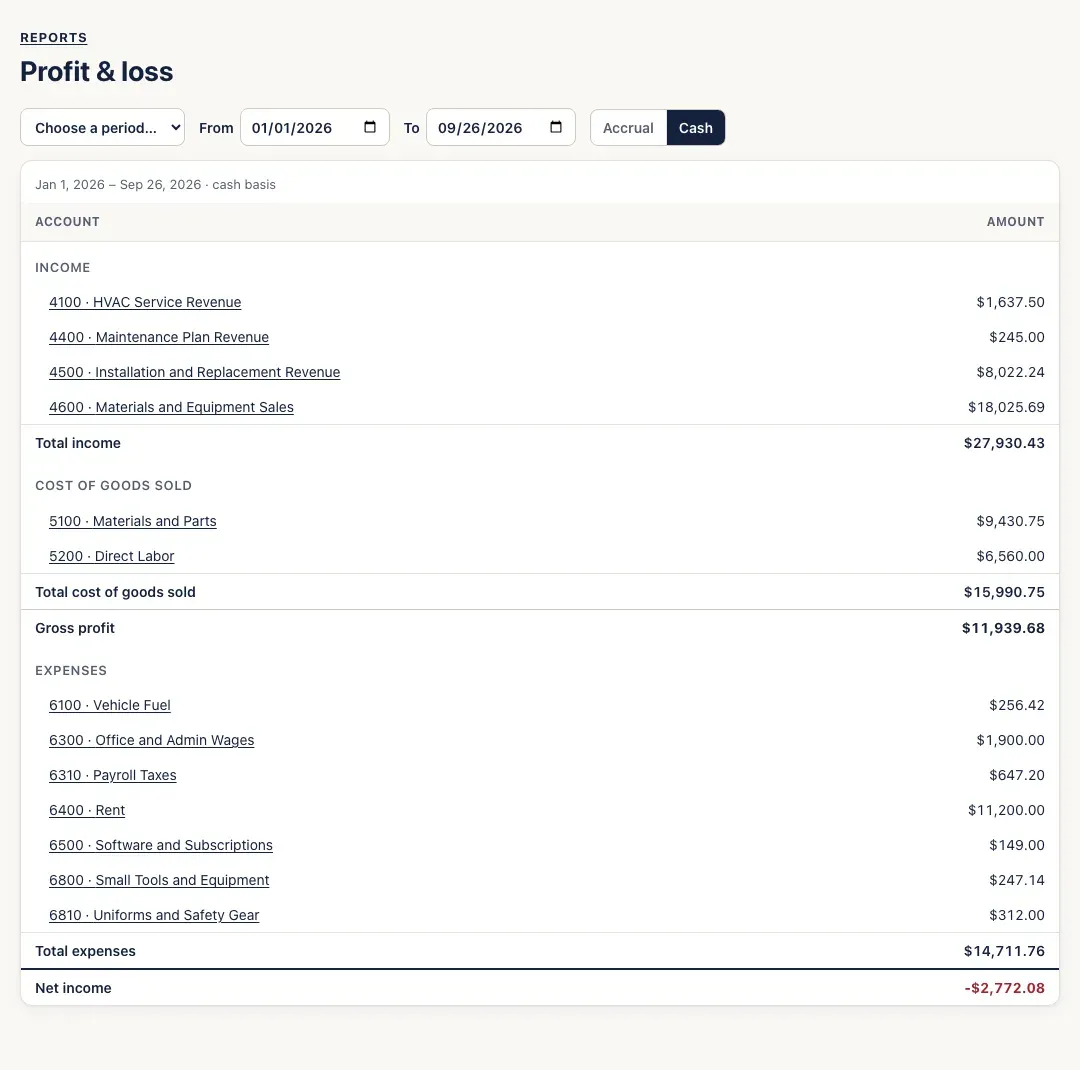
-
Click any account to see the postings behind its number (its general ledger for the same dates).
You’ll know it worked when…
Section titled “You’ll know it worked when…”The line at the top of the report shows your dates and accrual basis or cash basis, and Net income at the bottom is income minus cost of goods sold and expenses.
Notes & limits
Section titled “Notes & limits”- Gross profit is income minus cost of goods sold (materials, direct labor, subcontractors and other job costs). Other income and Other expenses (such as interest) show only when there are some.
- On the cash basis, a partly paid invoice counts in proportion — pay half, and half of each of its lines counts.
- Journal entries that record something owed — a line on Accounts Receivable or Accounts Payable — count only on the accrual basis: no money has moved yet.
- A closed month’s cash-basis numbers don’t change later: payments can’t be applied with a date in a closed month.
- Net income can be negative; it shows in red with a minus sign.
- Everything you chose is in the page’s link, so you can bookmark it or send it to someone on your team.